JP Morgan’s latest upgrade follows three consecutive months of comfortable consensus beats, with both June and July seeing GGR up by 19% compared with the same month last year.
The sudden surge from Macau’s gaming sector is, according to JP Morgan analysts, is likely due to consumers viewing positively recent stock rallies in China, Hong Kong and the US, as evidenced by similar surges in Hong Kong retail Swiss watch exports and mainland luxury malls. It is also attributed to easier access to Hong Kong dollars on the bank of Hong Kong’s recent liquidity boom – itself evidence by “huge IPO oversubscriptions and plunging HIBOR”.
Likewise, “high-profile concerts and events provide gamblers a compelling excuse for more frequent trips, boosting Macau’s allure and capturing greater wallet/time share from gamblers and families,” the investment bank explained.
It also downplayed concerns that the surge is unsustainable, arguing that “Macau’s up-cycles typically span at least three to four quarters, fueled by loss/win-chasing behavior – gamblers’ losses spur “revenge” returns, while wins tempt repeat visits, creating a self-reinforcing demand loop.
“With 2Q25 marking the first stand-out beat post-reopening, we believe Macau’s momentum has (long) legs through 1Q26E at least, capitalizing on easy comps.”
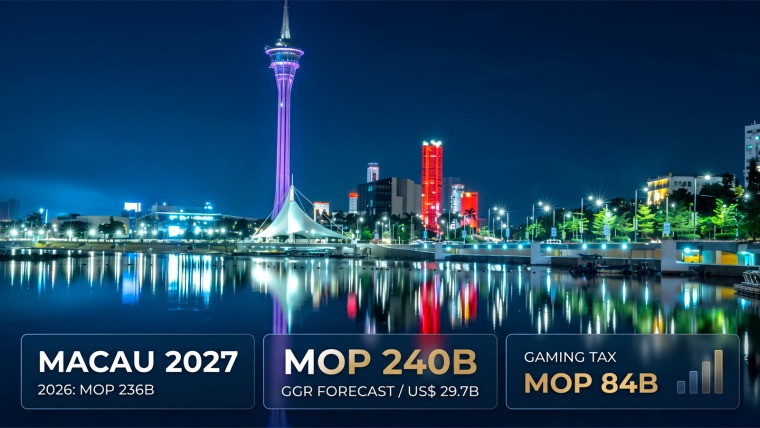
Macau GGR for the first seven months of 2025 combined sits at MOP$140.9 billion (US$17.4 billion), representing a 6.5% year-on-year increase.