“However, junket (or VIP) volume will likely stay near current low levels unless regulations change. Total GGR, therefore, will likely be 80%-85% of 2019 levels,” the credit rating agency says.
Melco Resorts (Macau) and Sands China are expected to experience accelerated EBITDA growth thanks to new enhancements or updated properties.
It was pointed out that MGM China Holdings has already exceeded its pre-pandemic EBITDA figures. The rest of the casino operators are projected to reach roughly 90 per cent of the 2019 EBITDA levels this year.
The credit rating agency has also flagged the potential impact of economic headwinds and higher operating expenses aimed at attracting more premium mass players, saying it could “impair Macao cash flow and leverage improvement”.
“Development projects could delay deleveraging or add incremental leverage. U.S. operators Las Vegas Sands Corp., Wynn Resorts Ltd., and MGM Resorts International will likely bid for three full-scale New York casino licenses,” it also added.
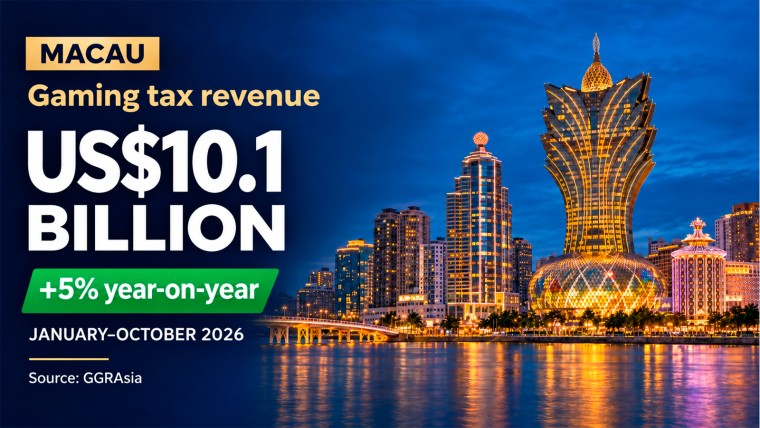
Macau recorded a GGR of MOP226.78 billion (US$28.25 billion) for 2024, marking an increase of nearly 24 per cent on the previous year.
The total surpassed the government’s forecast of MOP216bn for the year. The prediction for 2025 is MOP240 billion – about 11 per cent higher than the 2024 forecast.